
Strata Valuers Western Sydney: What Happens When Buildings Are Underinsured in Parramatta and Penrith
Most owners corporations don’t think about building insurance until something goes wrong. A storm takes part of a roof, a fire guts a level, and the claim comes back with a shortfall nobody budgeted for. In Parramatta and Penrith, where strata complexes range from 1970s walk-ups to brand-new high-rise, that gap can be bigger than people expect.
This article explains what underinsurance means for a strata scheme, how it affects owners’ pockets and what you can do about it. It also covers why the figure on your insurance certificate might not match today’s rebuild cost and how strata reinstatement cost assessments can help check the difference.
Summary
A strata building is underinsured when its insured value is lower than the cost to rebuild it. Insurers may then reduce what they pay on a claim, and the owners corporation has to cover the difference, usually through a special levy shared by unit entitlement. The gap often comes from old valuations, rising construction costs and rebuilding requirements that weren’t factored in. Owners corporations in Parramatta, Penrith and across Western Sydney can reduce the risk by getting a current replacement valuation, checking that the sum insured matches it and reviewing it regularly, especially after renovations or major cost changes.
How Strata Valuers in Western Sydney Work Out Replacement Cost
Strata valuers in Western Sydney usually start with one question: what would it cost to rebuild this building, on its current site, with materials and standards comparable to what’s there now? That figure is called the replacement cost or reinstatement value, and it’s the number that should sit behind your building insurance.
Replacement cost isn’t market value
This is the misconception that causes the most trouble. Owners often assume the insured amount should be close to what the building would sell for. It usually isn’t, and for good reason.
| Market value | Replacement (insurance) value | |
| What it measures | Price a buyer would pay for the property | Cost to rebuild the building if it were destroyed |
| Includes land? | Yes | No |
| Driven by | Demand, location, recent sales | Materials, labour, site works, current building codes |
| Used for | Sale, lending, tax purposes | Setting the sum insured on a policy |
A strata unit in Parramatta might sell for a strong price because of its location, but the land is not part of the insurance calculation. The building’s rebuild cost could be quite different from its sale price in either direction.
What Underinsurance Means for an Owners Corporation
Under the Strata Schemes Management Act 2015 (NSW), an owners corporation must insure the building for its full replacement value. The Act is the starting point, but the practical consequences come from how insurance policies work when the sum insured falls short. You can check the current wording on the NSW Fair Trading website, as the rules are updated from time to time.
The average clause
Some building insurance policies include an average clause, sometimes called a co-insurance clause; whether it applies to a strata claim depends on the policy wording. If the sum insured is less than the full replacement value, the insurer pays only a proportion of the claim.
Here’s a simplified example. Suppose a 12-storey building would cost $20 million to rebuild today, but it’s insured for $14 million. A fire causes $1 million in damage. Under an average clause, the insurer may pay 14/20 (70%) of the claim, which is about $700,000 before the excess. The owners corporation has to fund the remaining $300,000 plus the excess.
This is an illustration only, not a real event, and the exact result depends on the policy wording and the figures involved. The point is that the shortfall lands on owners, even though they paid premiums.
Special levies and unit entitlements
When an owners corporation has to pay for repairs or a shortfall that insurance doesn’t cover, it usually raises a special levy. These levies are shared among lot owners according to their unit entitlement.
Unit entitlement is the number that sets each lot’s share of the scheme’s costs and voting rights. It’s not the same as the size of the unit or the price it would sell for, which is why two apartments of similar size can carry different unit entitlements. If your building is underinsured, the cost of closing the gap is spread across all lots based on those entitlements, so a lot owner with a small share can still face a noticeable bill.
Why Buildings in Parramatta and Penrith End Up Underinsured
Western Sydney has a wide mix of strata stock, and each type has its own risk of underinsurance.
Older complexes
Many strata complexes in the Parramatta and Penrith areas were built in the 1970s, 1980s and 1990s. These buildings often include brick veneer, tiled roofs, older plumbing and wiring, and features that are expensive to replicate today. If the sum insured was set decades ago and never reviewed, it may be well below current rebuild costs.
Newer high-rise and mixed-use developments
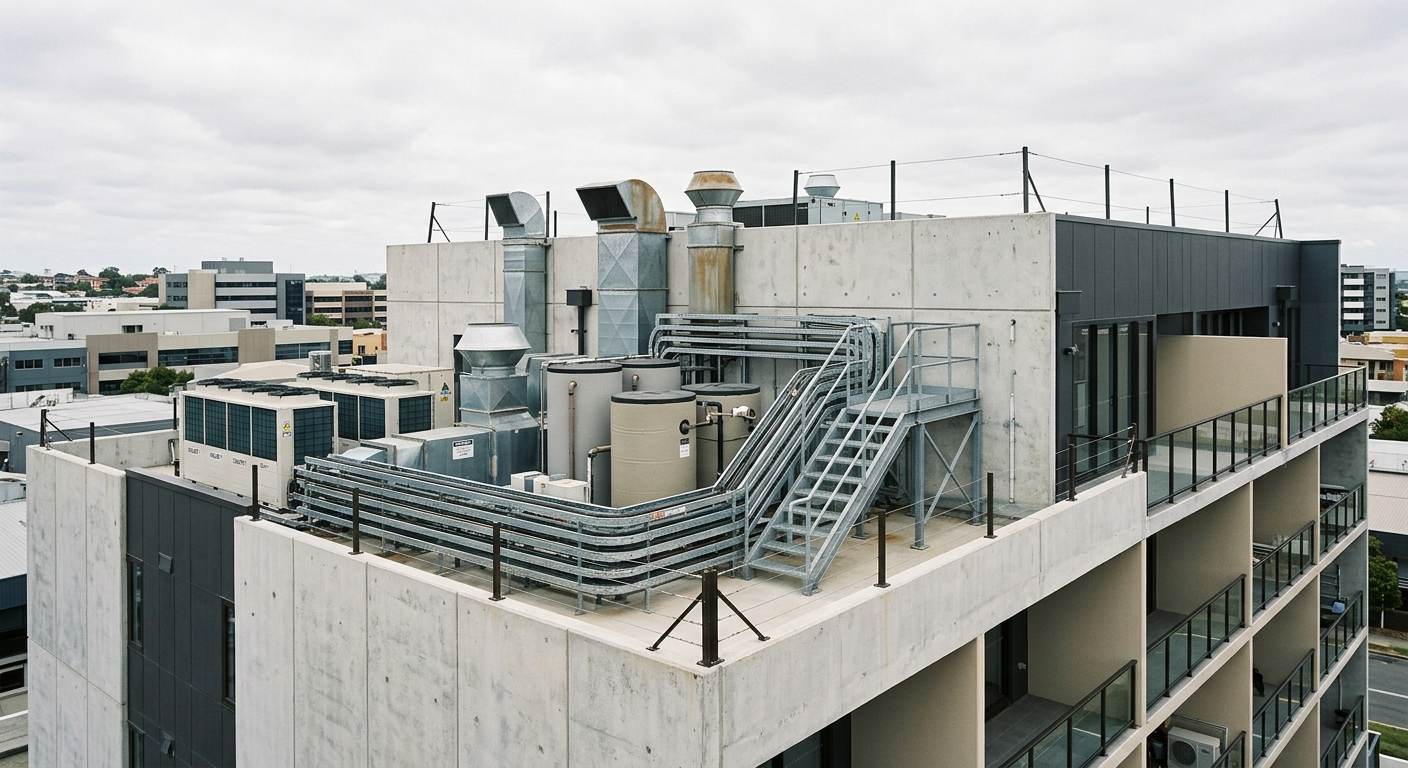
Parramatta’s CBD has seen a lot of high-rise apartment development, and newer buildings often have sophisticated services, lifts, podiums and facade systems. These are costly to rebuild. Some owners corporations take out cover based on the developer’s original figures, which may not reflect today’s costs.
Rebuilding to current standards
This is a common blind spot. After a major loss, you can’t always rebuild exactly what was there. Current building codes, fire safety requirements and council conditions may require upgrades, and demolition and site clean-up costs can add up quickly. A replacement valuation should account for these factors, not just the cost of materials.
Costs that have moved without a review
Construction costs have changed considerably in recent years. An insured value that was reasonable three or four years ago can fall short today without anyone noticing, because the policy renews automatically and the premium looks fine.
Common Misconceptions
- “The insurer’s figure is always accurate.” Insurers often use estimates or software calculations that may not reflect the actual building. A proper valuation looks at the specific building, its features and its site.
- “A cheaper premium means we’re getting a better deal.” A lower premium can mean a lower sum insured, which may leave the scheme exposed when a claim happens.
- “Our building is insured, so we’re covered.” Insurance is only as good as the amount insured. Being insured is not the same as being adequately insured.
- “Replacement value and market value are the same thing.” As the table above shows, they measure different things.
- “Lot owners don’t need to worry about this.” Lot owners share the cost of any shortfall, and their own policies may not cover improvements or fixtures they’ve added.
What a Replacement Valuation Involves
A replacement valuation for a strata scheme typically looks at the building’s size, construction type, finishes, services and common property. The valuer considers current construction costs for comparable work in the area, along with allowances for professional fees, demolition and compliance upgrades. The result is a written report with a replacement figure, the assumptions used and the date of valuation.
Costs for these reports vary with the size and complexity of the scheme, so it’s worth getting more than one quote and checking what each one includes. Ask whether the valuer inspects the property or relies on desktop estimates, and whether the report will be accepted by your insurer and strata manager.
Practical Steps for Owners Corporations and Lot Owners
- Get a current replacement valuation from a qualified valuer who understands strata schemes.
- Compare the sum insured against the valuation and raise any gap with your strata manager and insurer.
- Read the average clause in your policy so you know how a claim would be assessed.
- Review the valuation regularly and check how often a strata building’s replacement cost should be reassessed, particularly after renovations, major repairs or noticeable changes in construction costs.
- Keep records of the valuation date, insurance schedules and any upgrades to the common property.
- Lot owners should check their own policies to confirm coverage for improvements, fixtures and contents that the owners corporation policy doesn’t include.
Frequently Asked Questions
What’s the difference between an insurance valuation and a market valuation for a strata building?
An insurance valuation estimates the cost to rebuild the building, while a market valuation estimates what the property would sell for. Insurance valuations exclude land and focus on construction costs, while market valuations reflect demand and location.
How often should an owners corporation update its insurance valuation?
There’s no single fixed timeframe that suits every scheme. Many owners corporations review their valuation every few years, and sooner after renovations or significant changes in building costs. Your strata manager and insurer can advise on what’s appropriate for your building.
Who pays if the building is underinsured?
Usually the lot owners do, through a special levy shared according to unit entitlement. The owners corporation has to fund any gap between the insurance payout and the actual cost of repairs.
Does the owners corporation’s insurance cover the inside of my apartment?
It depends on the policy and how the scheme is set up. The owners corporation policy typically covers the building and common property, but it often excludes lot owners’ improvements, fixtures and contents. Check your own policy carefully.
Can an insurer reduce a claim if the building is underinsured?
Yes, if the policy includes an average clause or similar wording. The payout may be reduced in proportion to the shortfall. The exact effect depends on the policy terms.
Conclusion
A strata building that’s underinsured can leave owners facing a bill they didn’t expect. The gap usually comes from insured values that haven’t kept pace with rebuild costs, not from any single mistake. Replacement cost is a different measure from market value, and it’s the figure that matters for insurance. Regular reviews and a current valuation are the most practical way to keep your scheme protected.
If you’re not sure whether your scheme’s insured value reflects today’s rebuild cost, Western Sydney Valuations can prepare a replacement valuation for strata schemes across Parramatta, Penrith and the wider Western Sydney area. Call +61 438 080 786 to talk through your building and what a valuation would involve.